India has no separate gift tax, but gifts above Rs 50,000 per year are taxed as income at your slab rate (5-30%). Gifts from relatives, wedding gifts, and inheritances are fully exempt with no limit. The recipient pays tax, not the donor.
Gift Tax in India 2026: Taxability, Exemptions and How to Report Gifts
India abolished its dedicated Gift Tax Act in 1998, but gifts are still taxed under the Income Tax Act. Section 56(2)(x) taxes gifts received by an individual or HUF above Rs 50,000 in a financial year as “income from other sources” at the recipient’s applicable slab rate. But not all gifts are taxable — gifts from relatives, marriage gifts, and inheritances are fully exempt. This guide explains exactly what is taxable, what is exempt, and how to report.
- Gifts above Rs 50,000/year are taxable as income at your slab rate (up to 30%)
- The threshold is aggregate for the year — not per gift
- Gifts from relatives are fully exempt regardless of amount
- Wedding gifts are exempt — no monetary limit
- Property gifts are valued at stamp duty value; movable property at fair market value
What Is the Gift Tax Rate in India and Who Pays It?
India does not have a separate “gift tax rate” — gifts are taxed as regular income. If you receive a taxable gift, the entire gift amount is added to your “income from other sources” and taxed at your applicable income tax slab rate:
| Taxable Income (New Regime FY 2026-27) | Tax Rate |
|---|---|
| Up to Rs 4,00,000 | Nil |
| Rs 4,00,001 to Rs 8,00,000 | 5% |
| Rs 8,00,001 to Rs 12,00,000 | 10% |
| Rs 12,00,001 to Rs 16,00,000 | 15% |
| Rs 16,00,001 to Rs 20,00,000 | 20% |
| Rs 20,00,001 to Rs 24,00,000 | 25% |
| Above Rs 24,00,000 | 30% |
The gift is taxed in the year it is received, regardless of when the donor gave it. The recipient pays the tax — not the donor (the Gift Tax Act 1958, which taxed the donor, was repealed in 1998).
Which Gifts Are Exempt from Tax Under Section 56(2)(x)?
| Type of Gift | Exemption | Limit |
|---|---|---|
| Gift from a relative (defined list) | Fully exempt | No limit |
| Wedding gift (on occasion of marriage) | Fully exempt | No limit |
| Gift received by will or inheritance | Fully exempt | No limit |
| Gift in contemplation of death of donor | Fully exempt | No limit |
| Gift from local authority / government / approved charity | Fully exempt | No limit |
| Gift from non-relative, non-exempt source | Taxable if aggregate exceeds Rs 50,000 | Rs 50,000 per year threshold |
Who Qualifies as a “Relative” for Gift Tax Exemption?
The Income Tax Act 1961 defines “relative” for Section 56(2)(x) purposes as:
- Spouse of the individual
- Brother or sister of the individual
- Brother or sister of the spouse
- Brother or sister of either parent
- Lineal ascendants or descendants of the individual (parents, grandparents, children, grandchildren)
- Lineal ascendants or descendants of the spouse
- Spouse of any of the above
How Are Property and Shares Taxed When Gifted?
Section 56(2)(x) covers not just cash gifts but also immovable property and movable property (shares, jewellery, etc.) received without consideration (free) or for inadequate consideration:
- Immovable property received free: Stamp duty value (SDV) is taxable if it exceeds Rs 50,000
- Immovable property bought below SDV: If SDV exceeds purchase price by more than Rs 50,000 or 10% of purchase price, the difference is taxable
- Movable property (shares, gold, jewellery) received free: Fair Market Value is taxable if aggregate exceeds Rs 50,000
- Movable property bought below FMV: FMV minus consideration is taxable if the difference exceeds Rs 50,000
How Do You Report Gifts in Your Income Tax Return?
Taxable gifts must be reported under Schedule OS (Income from Other Sources) in your ITR. Exempt gifts (from relatives, on marriage, by inheritance) do not need to be reported but it is good practice to maintain a gift deed or documentary evidence to prove the exemption if questioned. Key steps:
- Use ITR-1 or ITR-2 (not ITR-1 if income from other sources includes taxable gifts above Rs 50,000)
- In Schedule OS, disclose gift under “Any other income”
- Advance tax is payable if total tax liability exceeds Rs 10,000 in the year
- Maintain a gift deed for all significant gifts — especially property and shares
Are Gifts to a Company or LLP Taxable?
Section 56(2)(x) applies to individuals and HUFs only. If a company or LLP receives a gift, the taxability depends on the nature of the receipt. Generally, a gratuitous inflow of capital to a company is not income. However, if shares are issued to a company below Fair Market Value (Section 56(2)(viib) for closely held companies) or property is transferred at below-market value, separate anti-abuse provisions apply. Tax advice is essential before executing any large gifts to or from corporates.
Frequently Asked Questions
There is no separate gift tax rate. Gifts above Rs 50,000/year are added to your income and taxed at your applicable income tax slab rate (5% to 30% depending on total income).
No — gifts from parents are fully exempt since parents qualify as “relatives” under Section 56(2)(x). Gifts from grandparents, children, siblings and their spouses are also exempt.
No — gifts received on the occasion of marriage are fully exempt from tax with no monetary limit, regardless of whether the donor is a relative or not. This applies only to the person getting married.
Rs 50,000 per financial year from non-relatives (aggregate). Above this limit, the entire amount (not just the excess) becomes taxable. Gifts from relatives, marriage gifts, and inheritances are exempt without any limit.
Not immediately for the donor — Section 47 exempts transfers by gift from capital gains tax for the donor. However, when the recipient later sells the property, capital gains are calculated from the original cost of acquisition by the donor.
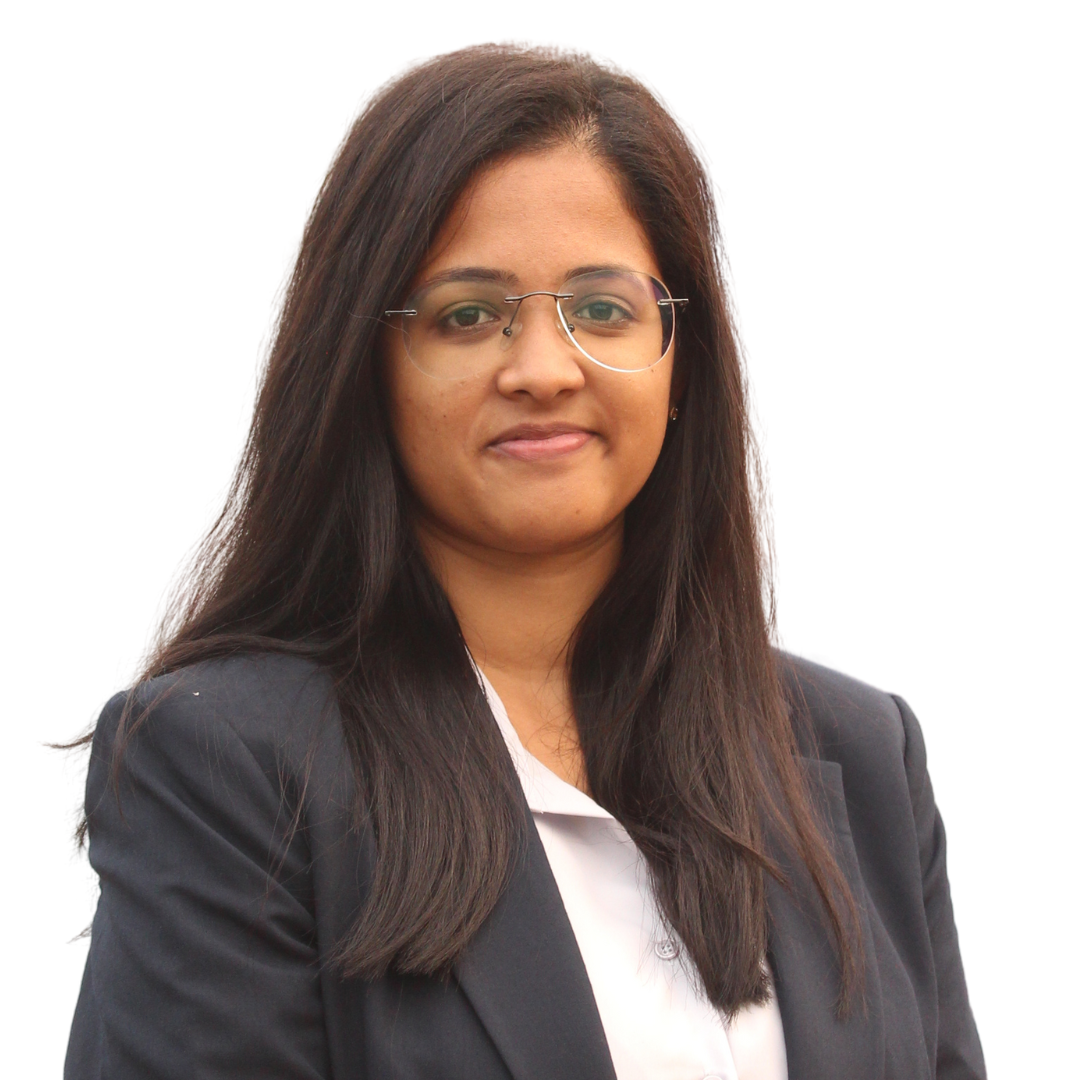
CA Madhusmita Padal is a Practicing Chartered Accountant with firms based in Odisha and Chennai. She specializes in taxation, company law, and auditing. She is passionate about simplifying complex concepts and making knowledge accessible to all.